Credit Genie
- 4.7
- Rating
- 1.00M
- Installs
- Free
- Price
 Analysis by App-foxy
I approached Credit Genie: Get Cash Advance as a practical finance app rather than a general budgeting tool. Its purpose is straightforward: help people explore access to cash when an unexpected expense arrives and provide a more convenient starting point than searching through several financial services separately. That focus makes it easy to understand, but it also means you should use it with a clear plan. A cash advance can solve a short-term timing problem, yet it is not a substitute for stable income or a long-term debt strategy.
In my experience, the app makes the most sense for someone who wants to investigate available options from a phone, compare the next steps carefully, and keep an urgent request separate from everyday spending. It is less suitable for anyone expecting guaranteed approval, instant relief without conditions, or a complete replacement for a bank account. The difference between those expectations matters more here than the app’s simple presentation.
How Credit Genie fits into a real financial emergency
The most useful way to think about this app is as a bridge between a financial need and the services that may help address it. Imagine a bill is due before payday, a car repair cannot wait, or a household expense arrives at an awkward time. Instead of treating the app as free money, I would use it to understand whether a cash-advance route is appropriate, what information may be required, and whether the repayment timing fits my next income date.
You May Also Like

 Blood Strike: 2.5 Anniversary
Blood Strike’s Loadouts Turn Every Drop Into a Tactical Gamble
A close look at Blood Strike’s custom loadouts: how fast access to signature weapons reshapes its battle royale rhythm, rewards preparation, and narrows the gap between fights.

 Pandora - Music & Podcasts
Pandora’s Music Is Easy to Start, but Harder to Recover
Pandora’s strength is its low-effort path from a seed to a station. Its weak spot is how much confidence it asks you to place in connection, setup, and quiet recovery.

 8 Ball Pool
 Is Built on Rivalries, Rematches, and Routine
A close look at the rivalries, rematches, shared routines, and unanswered safety questions that turn a quick pool match into a persistent mobile community.

 Samsung Music
’s Quiet Strength Is Playing What You Already Own
Its reach comes less from spectacle than from dependable access to a personal library. That simplicity is both the app’s strongest retention engine and its ceiling.

 AccuWeather: Weather Radar
AccuWeather Review: A Quick, Clear Forecast for Everyday Decisions
For everyday plans, the best forecast is the one you can understand quickly. AccuWeather makes rain timing, radar, and local conditions easy to act on, with a few trade-offs.

 Hill Climb Racing
Why Hill Climb Racing Still Turns Crashes Into One More Run
A tiny car, a bumpy hill and one more upgrade: Hill Climb Racing keeps resurfacing because its simple chaos makes every near-miss feel personal.
More From Our News Desk



That last check is essential. Before starting, I would write down the amount needed, the date the money would be available to repay it, and the other bills competing for that same income. If the repayment would leave you short again, the app cannot fix the underlying problem. In that situation, asking the bill provider for more time, using an existing emergency fund, or speaking with a bank may be safer than adding another obligation.
Credit Genie is free to install, which lowers the barrier to trying it. The app is published by Creditly Corp and sits in the finance category, with an Everyone content rating. Its reach is meaningful: it has passed one million installs, with an average score of 4.1 from around 57 thousand ratings and roughly 7.5 thousand written reviews. Those figures suggest that many people find the concept useful, while also reminding me that a finance app should be judged by fit and transparency, not popularity alone.
What the current version tells me
The current release is version 3.1.1, and the app supports operating systems from version 10 onward. That gives it a reasonably modern compatibility range for many Android users. I would still check the operating system on an older phone before planning around it, especially if the device has limited storage or has not received recent security updates.
The app was released on October 18, 2021, so it is not a brand-new experiment. Its continued presence and large install base make it feel more established than a newly published finance utility. At the same time, longevity should not be confused with a promise that every request will work for every person. Eligibility, available offers, repayment terms, and the final cost remain the parts I would examine most closely before accepting anything.
One practical advantage of the current release is that it gives users a single place to begin rather than forcing them to remember several different services. That can reduce the mental load during an emergency. The trade-off is that convenience can make a decision feel quicker than it really is. I would slow down at the point where an offer, repayment amount, or authorization is presented and read every line before continuing.
How I would use it without losing control
My first step would be to open the app only when I know the exact purpose of the request. “I need some money” is too vague. “I need enough to cover this specific expense until this specific income arrives” is a much safer starting point. A defined target helps prevent borrowing more than necessary simply because an available amount looks attractive.
Next, I would prepare the basic details needed to complete the process and make sure they are accurate. Rushing through financial forms increases the chance of mistakes, delays, or confusion later. I would also use a private connection, keep the phone’s operating system updated, and avoid entering sensitive information on a shared device. These are simple habits, but they matter more in a finance app than in an ordinary entertainment download.
After reviewing an option, I would compare the total repayment with the amount received, not just the headline advance. I would also note the repayment date and place a reminder on my calendar. A useful workflow is to create that reminder before accepting anything. If the date conflicts with rent, utilities, or another fixed payment, that is a warning to reconsider the request rather than hope the timing works out.
A second helpful habit is to save a private record of the agreement details after completing the process. I would keep the amount, expected repayment date, and any relevant confirmation in a secure location. That makes it easier to check what I agreed to without relying on memory when the next payday arrives.
Where it can help more than the usual alternatives
Compared with visiting a traditional bank branch, a phone-based cash-advance app is more convenient for a small, time-sensitive need. You can begin outside normal branch hours and avoid an appointment. Compared with borrowing from a friend, it also keeps the request private and avoids putting a personal relationship under pressure.
That convenience has limits. A bank or credit union may be the better choice if you already have an established account, need a larger structured loan, or want a human adviser to explain the cost. A credit card may be preferable for a purchase when you can repay it reliably and already understand its terms. An employer-based advance or a negotiated payment extension may also fit better when the problem is simply a mismatch between a bill date and payday.
I would not use Credit Genie as a substitute for a detailed budget app. Its value is connected to a short-term cash need, not to tracking every category of spending over many months. If your main goal is to reduce recurring expenses, build savings, or understand where your money goes, a dedicated budgeting tool or a spreadsheet will usually provide a clearer view.
The effect on existing users
For someone already using the app, the current version should be approached as a working tool rather than a reason to borrow more often. An update can make an experience smoother, but it does not change the basic responsibility of checking the repayment impact. I would review the app after updating, confirm that the account information still looks correct, and make sure any reminders or personal notes remain accessible.
Existing users may appreciate having a familiar starting point when another unexpected expense appears. Familiarity can be useful because it reduces the time spent learning a new interface. It can also create overconfidence. The fact that a previous request worked does not mean a future request will have the same result, amount, timing, or conditions. I would reassess every request from the beginning.
There is also a psychological benefit to separating an emergency decision from a shopping decision. I would avoid opening the app casually or treating an available advance as extra spending room. Using it only for a named need makes it easier to judge whether the repayment is worth the short-term relief. This is one of the most important safeguards because the app’s convenience can otherwise encourage repeated use.
If you are helping a family member decide whether to use it, I would not simply tell them to download it. I would ask three questions: what exact expense is being covered, when can the money be repaid, and what bill will be reduced or delayed to make room for repayment? If those answers are unclear, the better next step may be advice from a bank, nonprofit counselor, employer, or trusted person rather than an immediate application.
Friction and gaps I would take seriously
The biggest limitation is not necessarily the interface; it is the uncertainty that surrounds any cash-advance decision. A user may want a definite amount at a definite time, while the eventual result can depend on eligibility and the terms shown during the process. I would not make a rent, medical, or utility deadline depend entirely on an assumption that an advance will arrive.
Another limitation is that a fast digital process can hide the emotional pressure behind the decision. When money is tight, even a modest repayment can affect groceries, transportation, or another essential. I would calculate the following pay period in full before proceeding. If the repayment leaves no room for normal necessities, the app is not solving the emergency; it is moving the stress a short distance into the future.
I would also be cautious about entering information before understanding why it is needed and how the process works. In any finance product, read the screens carefully, avoid guessing, and stop if a request seems unrelated to the service you are trying to use. The app may be convenient, but convenience should never replace basic privacy awareness.
People looking for a permanent credit-building solution should manage their expectations. A cash advance is designed around short-term access, not automatically around building a stronger financial history. If your goal is improving credit, compare products specifically intended for that purpose and examine their reporting and costs separately. If your goal is consolidating debt, a structured loan or professional advice may be more appropriate.
Who should choose it, and who should skip it
I can recommend considering Credit Genie to an adult who has a clearly defined short-term gap, understands that approval and terms are not guaranteed, and can identify a realistic repayment source. It is particularly convenient for someone who prefers handling the first stage from a phone and wants to avoid immediately visiting a branch or asking a friend for help.
I would advise skipping it if you are already juggling several advances, regularly run out of money before payday, or cannot explain how the repayment will fit into your budget. It is also not the right first choice for a large expense, an ongoing income problem, or a situation where you need a person to walk you through every detail. In those cases, a bank, credit union, employer resource, payment-plan negotiation, or financial counselor may offer a more suitable path.
The Everyone rating makes the app broadly accessible from a content perspective, but that does not mean every financial situation is appropriate for its use. Younger users and anyone unfamiliar with borrowing should involve a responsible adult or qualified adviser before accepting a financial obligation. Accessibility and suitability are different questions.
What I would watch before relying on it
I would pay attention to how clearly the app presents the amount received, the amount repaid, the timing, and any conditions attached to an option. Clear information should be easy to identify before a final decision. If I had to search through several screens to understand the total commitment, I would treat that as a reason to pause.
I would also watch how the product evolves in later releases. Version 3.1.1 is the current point of reference, but future updates may change navigation, eligibility flows, or the way information is displayed. I would read update notes and recheck important screens after an update instead of assuming the process is identical to the last time I used it.
Another thing worth watching is whether the app remains useful for occasional emergencies without encouraging a cycle of repeat advances. My personal test would be simple: after using it once, can I return to normal spending and repay on schedule without needing another advance? If the answer is no, the problem is bigger than the app and deserves a broader financial solution.
Finally, I would keep the app’s strong point and its main risk in view at the same time. Its strong point is the convenience of starting a short-term cash search from a mobile device. Its risk is that a convenient process can make borrowing feel routine. Use Credit Genie as a carefully checked emergency option, not as an extension of your regular income.
My overall view is cautiously positive. Creditly Corp has built an accessible finance app with a clear short-term purpose, a free entry point, and enough adoption to make it familiar to many users. I would recommend it only after checking the repayment plan against real bills and considering less costly alternatives first. Used selectively and with attention to the full commitment, it can be a useful tool during a temporary cash gap. Used repeatedly without a repayment plan, it is unlikely to address the reason the gap keeps appearing.
FAQs for Credit Genie
01What is Credit Genie and how does it work?
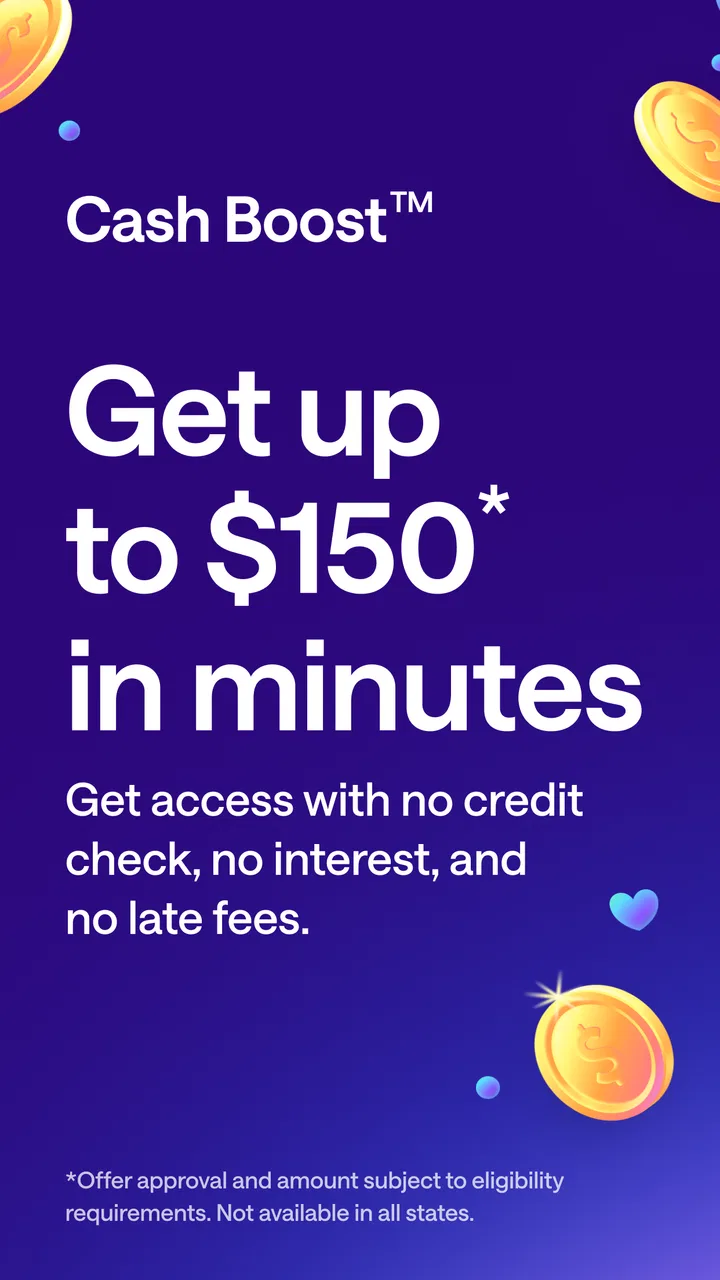
Credit Genie is a financial app designed to offer cash advances to users who need immediate funds. It connects to your bank account to assess your financial health and determine how much you can borrow. The app provides a seamless, user-friendly interface to request and receive funds quickly, usually without a credit check.
02Is using Credit Genie safe for my personal data?
Yes, Credit Genie prioritizes user security by employing advanced encryption and security protocols to protect your personal and financial information. The app ensures that your data is safe from unauthorized access, and it complies with industry standards for data protection and privacy.
03Are there any fees associated with using Credit Genie?
Credit Genie typically charges a small fee for each cash advance, which is disclosed upfront before you accept the advance. The app prides itself on transparency, so you won’t encounter hidden fees or surprise charges, allowing you to make informed decisions about borrowing.
04How quickly can I receive funds from Credit Genie?
Once you apply for a cash advance through Credit Genie, the funds are usually transferred to your linked bank account within minutes. However, the exact timing might vary depending on your bank’s processing times. The app is designed to provide fast access to funds when you need them most.
05Does using Credit Genie affect my credit score?
Generally, Credit Genie does not perform hard credit checks, so using the app won’t directly impact your credit score. It focuses on providing a hassle-free borrowing experience without affecting your credit history. However, it's advisable to use the service responsibly to maintain financial health.
Pros
- Quick cash advances up to $100.
- No credit check required to apply.
- Simple and user-friendly interface.
- Instant approval and fast deposit.
- Helps manage financial emergencies.
Cons
- Limited to small loan amounts.
- Available only in certain states.
- Requires bank account link.
- Fees may apply for cash advances.
- No option for long-term loans.

Credit Genie
Gallery